Physical Silver vs. Silver ETFs: A Cost and Liquidity Comparison
Silver looks simple: a metal with a price. Owning it is less simple. You can hold coins or bars in your hand, or buy shares of a fund that holds silver in a vault. Both give exposure to the same market, but they fail in different ways when you need to sell, and they charge you differently along the way. The right choice usually comes down to how much you hold, how often you might sell, and whether you have a safe place to keep metal.
Two ownership models, two sets of plumbing
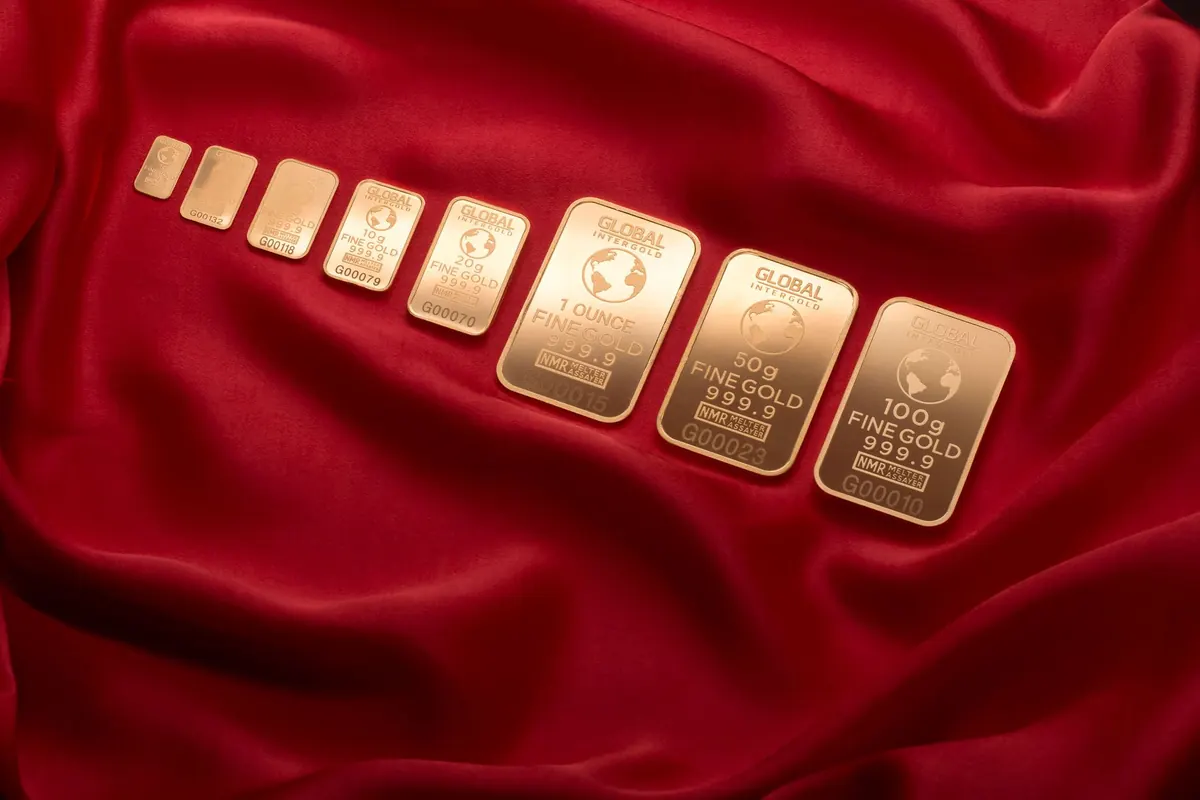
Physical silver means taking delivery of coins, rounds or bars. You pay the metal price plus a premium, then arrange storage, insurance and eventually a sale. The metal is an asset you possess, subject to the security you choose.
A silver ETF or exchange-traded commodity is a listed security. The fund or trust buys and stores bars with a custodian; you buy shares through a brokerage account. The share price tracks silver, minus fees and tracking differences. Most individual investors buy and sell shares on an exchange rather than redeeming metal. Some products allow large institutional redemptions; many do not offer delivery to small shareholders. Check the prospectus.
Neither model is “free”. One charges you at the dealer counter and in storage; the other charges you in the fund and in the market spread. Compare total cost, not headline price.
What you pay up front: premiums, spreads and commissions
For physical silver, the premium over spot is the first cost. A one-ounce coin from a recognized mint often carries a higher premium than a larger bar. Fractional coins carry higher again. You may also pay shipping, insurance, and a card or wire fee. Sales tax or VAT treatment varies by jurisdiction; in some places small investment coins are treated differently from large bars. Check local rules before ordering. The dealer’s buyback spread matters as much as the premium: the price at which they will buy back can be below spot or below your purchase price.
For an ETF, you pay a brokerage commission if your broker charges one, plus the bid-ask spread. The spread is the difference between the best buy and sell price; it can be small in liquid products and wider in smaller ones. You may also pay a premium to net asset value when buying and sell at a discount, especially when markets are stressed. The fund’s expense ratio is deducted from the fund’s assets, so it is not billed to you, but it reduces returns.
- Physical upfront: metal premium, shipping, insurance, payment fees, possible sales tax or VAT.
- ETF upfront: commission, bid-ask spread, possible premium to net asset value.
- Physical ongoing: safe, insurance, vault fees if stored professionally.
- ETF ongoing: expense ratio, account fees, possible custody or platform charges.
The costs you keep paying: storage, insurance and fund fees
Home storage is not free, even if it feels that way. A safe costs money; insurance may require a rider or separate policy; a bank safe deposit box has rent and access limits. Professional vault storage charges annual fees and may charge for withdrawals or inspections. For a small holding, the safe can cost more than the metal. For a large holding, insurance and vault fees become real line items.
ETF costs are easier to see but easy to ignore. The expense ratio is small in percentage terms, yet it compounds. A fund charging a modest annual fee will lag the metal price by roughly that fee over time, before tracking error. Your brokerage may also charge an annual account fee or a fee for holding foreign-listed products. Add those costs to the spread to get a fair comparison.
Rule of thumb: if you would not pay the annual storage cost in cash, do not assume the ETF is automatically cheaper. Run both numbers for your actual holding size.
Liquidity and exit options: speed versus control
Liquidity is not just “can I sell?” It is “can I sell quickly, in the size I want, at a price close to the metal value?” ETFs usually win on speed. During exchange hours, a liquid silver ETF can be sold in seconds through your broker. The trade settles in the usual settlement cycle, and the cash is available according to your broker’s rules. The main risks are a wide spread, a market-wide halt, or a discount to net asset value in a stress event. Those are not everyday events, but they are the moments when liquidity matters most.
Physical silver is liquid in a different way. You can sell to a local coin shop, an online dealer, a refiner, or a private buyer. Each route has a different spread and timeline. A local dealer may pay immediately but at a wider discount. An online dealer may quote a better price but require shipping and insurance, with payment after inspection. Private sales can fetch more but bring authentication, payment and personal safety issues. Large bars are harder to sell in small pieces; one-ounce coins are easier to move in a hurry.
- Decide the quantity you might sell and how quickly you might need cash.
- Get buyback quotes from at least two dealers before you buy, not only after.
- Keep invoices, assay certificates and original packaging; they can speed a sale.
- For ETFs, check the spread and trading volume during your usual trading hours.
Tracking, risk and the things that do not show up on a fee table
An ETF is a claim on a custodian’s vault, not metal in your hand. The structure matters: a fully allocated bar trust is different from a product using futures or lending. Read the prospectus for custody, insurance, redemption rights and fees. Counterparty and operational risk are small in well-run products, but they are not zero. Physical silver carries theft, loss and authentication risk. Insurance reduces the financial loss but adds cost; a safe reduces theft risk but not fraud if you buy from an unreliable source.
Tax treatment can also differ. In many jurisdictions, collectibles, bullion and securities are taxed differently, and reporting rules vary. Keep clean records of purchase dates, prices and fees for either route. This is not a reason to avoid one option, but it is a reason to compare after-tax outcomes, not just headline costs. For tax or legal advice, speak to a qualified professional in your jurisdiction.
A practical way to choose
Start with the job you want silver to do. If you want a small, tangible reserve that you can hold and possibly use locally, physical coins or small bars make sense, provided you have secure storage and accept the dealer spread. If you want to adjust exposure quickly, hold silver inside a brokerage account, or avoid storage logistics, a liquid ETF is usually more practical. If you are buying a large amount, compare professional vault storage with the ETF’s all-in cost; the answer can flip depending on the fee schedule.
Use this checklist before you buy:
- Calculate the all-in purchase cost: premium or commission plus spread plus taxes and shipping.
- Estimate the annual holding cost: storage, insurance, account fees, expense ratio.
- Check the exit price: dealer buyback quote or ETF bid-ask spread and volume.
- Confirm the tax treatment and record-keeping requirements.
- Choose the form you can store and sell without panic.
Neither route is universally cheaper. Physical silver gives you control and a tangible asset, but you pay for that control in premiums, storage and slower sales. Silver ETFs give you speed and easy pricing, but you own a fund share, not a coin, and you pay ongoing fees for the convenience. Match the structure to your holding size, your time horizon and your need for cash. If the numbers are close, choose the one you can administer calmly for years, not the one that looks cheapest on the day you buy.
Photo: Ron Lach / Pexels
How Recycled Silver Moves from Electronics to Refined Bars
Recycled silver travels a long road from circuit boards and old contacts to 999-fine bars. Here is how...
Silver Purity Marks for Beginners: 925, 958, and 999 Explained
A plain-English guide to silver purity marks — what 925, 958 and 999 mean, how to read the rest of a...
About Us